







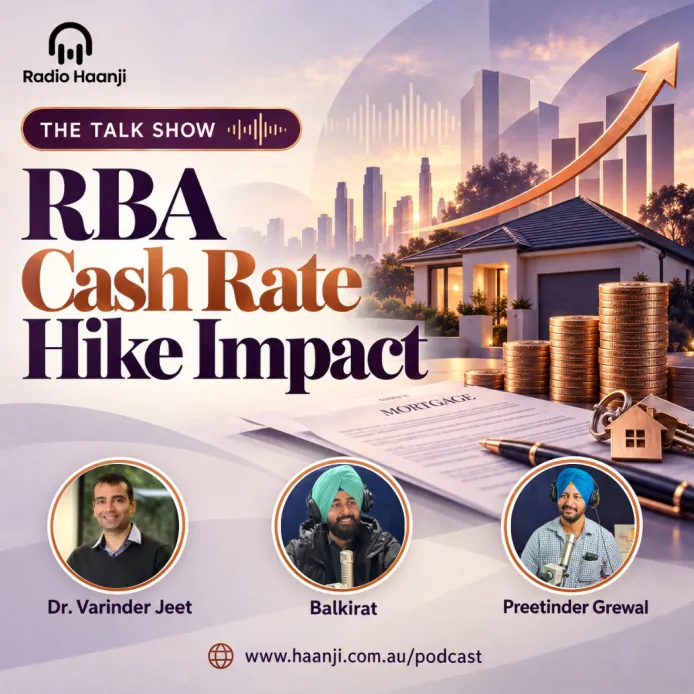
RBA Cash Rate Hike Impact: Mortgages & Cost of Living Breakdown
Host:-
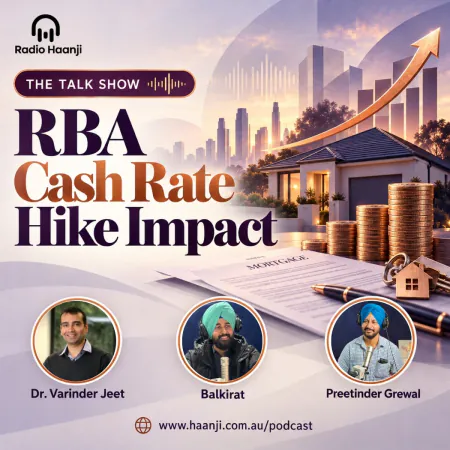
 Balkirat Singh
 Preetinder Grewal
Explore the RBA cash rate hike impact with Dr. Varinder Jeet on Radio Haanji's The Talk Show. Understand mortgages and inflation. Listen now!
The compounding pressure of monetary policy adjustments has placed household finances under intense scrutiny across the nation. On The Talk Show, broadcast on Radio Haanji 1674 AM, co-hosts Balkirat and Preetinder Grewal sat down with health economist and research fellow Dr. Varinder Jeet from Macquarie University in Sydney to dissect the real-world RBA cash rate hike impact. Rather than treating cash rate movements as abstract macroeconomic metrics, the discussion centered on the direct strain experienced by mortgage holders, small business operators, and essential workers.
Understanding these financial shifts requires looking past headline statistics and assessing baseline household budgets. As the Reserve Bank of Australia maintains restrictive settings to suppress stubborn consumer price pressures, everyday Australians face shrinking disposable income, tighter credit limits, and mounting utility expenses. By connecting macroeconomic indicators to personal balance sheets, this analysis delivers grounded clarity on current fiscal challenges.
Where to Listen
Catch the complete discussion on The Talk Show featuring Balkirat, Preetinder Grewal, and special guest Dr. Varinder Jeet on your preferred platform:
Episode Highlights
-
Official Monetary Policy Tightening: Examination of the RBA increasing the official cash rate by 25 basis points from 4.35% to 4.60%, marking the fourth rate hike within the calendar year.
-
Household Mortgage Repayment Pressure: Detailed calculations showing how an average $730,000 home loan incurs an extra $120 monthly expense, accumulating to nearly $480 per month across recent rate adjustments.
-
Credit Contraction and Sectoral Strain: Evidence that buyer borrowing capacity has contracted by roughly 10%, alongside construction cost increases of up to 45% driving homebuilder distress and corporate insolvencies.
-
Consumer Spending Reductions: Reports from local commercial and retail sectors showing revenue drops between 25% and 30% as discretionary spending recedes.
-
Regulatory Card Surcharge Changes: Discussion surrounding the federal decision to eliminate customer-facing debit and credit card merchant surcharges, alongside concerns regarding compensatory retail price adjustments.
-
Healthcare Sector Labor Unrest: Analysis of the Victorian public hospital doctors' four-hour stop-work action advocating for safer working hours and a 28% wage adjustment over four years while maintaining emergency services.
-
Intergenerational Household Adaptation: Observations on families turning toward joint and extended living arrangements to share energy bills, groceries, and housing liabilities during sustained living cost increases.
How Much Does the Latest RBA Cash Rate Hike Increase Monthly Mortgage Repayments?
A 25 basis point increase lifts the cash rate from 4.35% to 4.60%. For a standard Australian mortgage of $730,000, this single adjustment adds approximately $120 to monthly repayments. Across four consecutive increases within the year, cumulative repayments have surged by roughly $480 every month on equivalent principal balances.
For families managing variable-rate loans, these ongoing increases represent an immediate extraction of cash from discretionary household budgets. A borrower holding a $600,000 loan balance faces an extra $91 per month from a 0.25% shift, while balances of $750,000 incur approximately $114 in new monthly obligations. Over a full calendar year, these compounding rate hikes demand thousands of dollars in additional post-tax earnings simply to service existing debt.
The severity of the repayment surge varies depending on original loan terms and overall amortization schedules. Because earlier interest rate increases had already absorbed financial buffers, households find each subsequent basis point adjustment significantly more burdensome. The dialogue on Radio Haanji emphasized that these increments directly compete with essential non-discretionary expenses, compelling mortgagees to sacrifice savings reserves or re-evaluate fundamental household spending.
Why Does Rising Inflation Reduce Household Borrowing Capacity Across Australia?
Elevated interest rates lower consumer borrowing capacity by roughly 10%. When assessing mortgage applications, commercial lenders apply higher interest rate assessment buffers, restricting the maximum capital available to prospective buyers. Consequently, aspiring purchasers are priced out of entry-level housing markets even when localized property prices experience moderate downward corrections.
This credit contraction presents a challenging landscape for first-home buyers. Even if asking prices for properties drop from $850,000 to $800,000, a buyer whose qualified lending threshold drops from $800,000 down to $720,000 finds themselves further from a home purchase than before the price decline occurred. The theoretical advantage of softer home valuations is quickly erased by strict commercial bank debt-serviceability tests.
Simultaneously, the supply side of residential housing faces extreme cost escalation. Construction expenses have risen by up to 45%, leaving building contractors caught between fixed-price commitments and unsustainable operational overheads. This cost crunch has triggered rising builder insolvencies, slowing completions and creating an acute shortage of newly built housing stock across major population centers.
How Will the Merchant Card Surcharge Ban Affect Everyday Consumer Pricing?
The abolition of consumer card transaction surcharges removes checkout add-ons of 1% to 1.5% on debit and credit card purchases. However, because commercial merchants must still remit processing charges directly to payment network providers, retail operators may adjust base shelf prices upward to absorb merchant operating overheads.
Consumer transaction fees have drawn scrutiny from shoppers purchasing daily groceries, fuel, and casual dining services. While consumer protection initiatives seek to standardize point-of-sale costs, retail business models face rising commercial rent, utility overheads, and inventory expenses. Eliminating the itemized surcharge prevents businesses from passing costs transparently to cardholders at the terminal.
The risk raised during the broadcast is that merchant cost absorption frequently translates into across-the-board menu and shelf price adjustments. Rather than saving consumers money over the annual cycle, small businesses under margin pressure often incorporate payment processing allowances into their standard retail pricing, changing how transactions are settled without lowering total shopping expenses.
Global Supply Shocks, Energy Costs, and Persistent Domestic Inflation
Headline inflation across the nation remains stubborn at approximately 3.6%, sitting outside the Reserve Bank of Australia’s target band of 2% to 3%. A substantial driver of this continued inflationary pressure stems from international geopolitical unrest, particularly within key trade channels and the Middle East, which has sustained volatility across global energy and shipping markets.
Domestic diesel and petrol prices continue to fluctuate within ranges of $2.50 to $2.80 per liter, compounding freight and agricultural expenses throughout local distribution channels. Because transportation represents an unavoidable input for food delivery, raw manufacturing components, and consumer retail items, expensive fuel functions as a systemic tax on the entire domestic economy.
Commercial spending data reflects these pressures, with retail sectors documenting sales declines between 25% and 30%. Consumer confidence measures have retreated into negative territory, prompting households to trim recreational travel, hospitality dining, and discretionary leisure purchases in order to absorb essential utility and transport charges.
Public Sector Pressures and Victorian Healthcare Industrial Action
Cost-of-living increases have extended into public infrastructure and service delivery. In Victoria, public hospital doctors represented by their union organized a four-hour stop-work industrial action to highlight workplace fatigue, prolonged shifts, and unmanageable patient ratios. The medical workforce is pursuing a 28% wage adjustment phased over four years to restore earnings lost to persistent inflation.
While hospital emergency departments remained operational during the stoppage, elective clinical consultations and procedural rosters experienced rescheduling. This labor action illustrates the broader cycle of domestic price shifts: as basic living and housing costs elevate, public sector employees must seek wage corrections to avoid deep reductions in real earning power.
The tension between public sector salary growth and state budget constraints creates difficult administrative trade-offs. Governments seeking to manage fiscal deficits must balance wage stability against public sector retention, particularly within critical frontline environments like regional and metropolitan public healthcare systems.
Community Responses and Financial Adaptation Strategies
In response to escalating financial pressures, Australian households are increasingly modifying long-term living arrangements. Discussions on The Talk Show highlighted a pronounced shift toward extended and joint family households, where multi-generational relatives co-reside within a single dwelling.
Consolidating households allows families to combine income streams to service higher interest repayments while distributing recurring utility charges, council rates, and food bills across multiple working adults. This structural change reduces aggregate demand for separate rental units and lowers per-capita living expenses during periods of high inflation.
While multi-generational living requires lifestyle compromises regarding privacy and space, it provides a stable buffer against default and financial exhaustion. For many culturally diverse communities, returning to joint family living arrangements represents an effective, self-reliant response to sustained monetary tightening and rising living costs.
Key Takeaways
-
The Reserve Bank of Australia elevated the official cash rate by 25 basis points to 4.60%, marking the fourth official interest rate increase of the year.
-
An average Australian mortgage balance of $730,000 incurs an extra $120 in monthly repayment costs, generating a cumulative monthly burden increase of roughly $480 across recent hikes.
-
Lending capacity for prospective home buyers has contracted by approximately 10%, offsetting minor property price reductions through tighter commercial bank serviceability standards.
-
Residential construction input costs have surged by up to 45%, contributing to widespread builder insolvencies and constrained new dwelling completions.
-
National consumer inflation persists near 3.6%, remaining elevated above the RBA target window of 2% to 3% due to domestic transport costs and international energy price volatility.
-
Victorian public hospital doctors initiated a four-hour stop-work action seeking improved roster safeguards and a 28% salary adjustment spread across four years.
References and Further Reading
-
Reserve Bank of Australia (RBA) — Official Cash Rate Decision Statements and Monetary Policy Minutes.
-
Dr. Varinder Jeet (Macquarie University, Sydney) — Health Economics and Macroeconomic Public Policy Analysis.
-
Victorian Public Hospital Doctors Union — Stop-Work Action Reports and Healthcare Enterprise Agreement Negotiations.
To hear the comprehensive breakdown of Australia's economic landscape, listen to the full episode of The Talk Show with hosts Balkirat and Preetinder Grewal featuring guest Dr. Varinder Jeet on Spotify, Apple Podcasts, or directly via the Radio Haanji App.
Frequently Asked Questions
What was the RBA cash rate adjustment discussed on The Talk Show?
How does the current cash rate hike impact an average $730,000 mortgage?
Why are retail businesses worried about the merchant surcharge ban?
What factors are keeping Australian inflation above the target 2% to 3% band?
Why did Victorian public hospital doctors undertake industrial action?
How are Australian families adapting to persistent cost of living pressures?
What's Your Reaction?